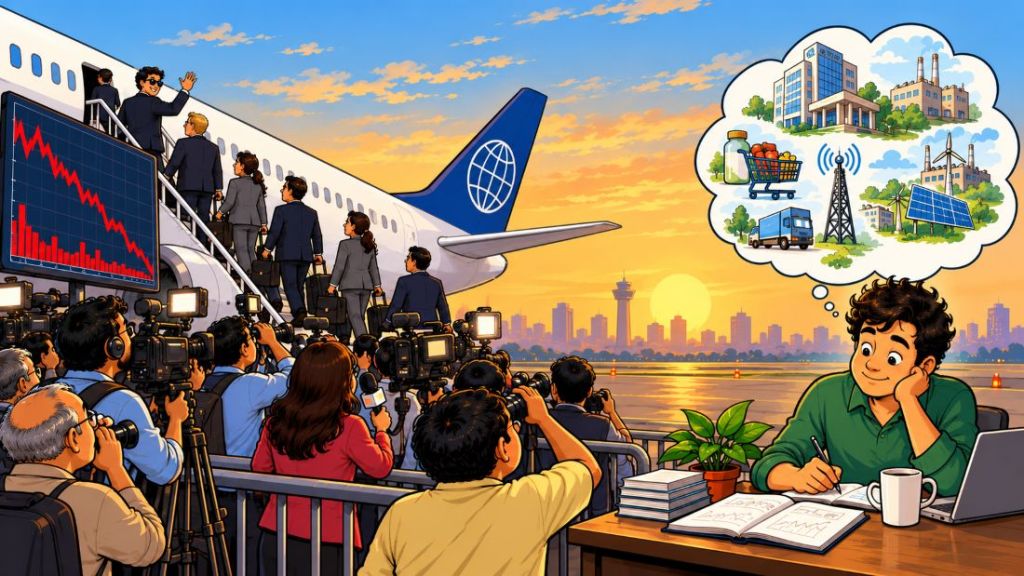
Today, every discussion about the markets seems to begin and end with FIIs, or foreign institutional investors. Why are they selling? When will they start buying? What will they buy first? Should we cut taxes to entice them?
And every time the markets fall a bit, the conversation repeats, as if stuck in a groove (for those who remember vinyl records). The commentators and experts then remind us that India is the fastest growing major economy, so FII buying is inevitable or even imminent.
However, we should remember that the selling decisions of FIIs may have little to do with the fundamentals of the Indian economy.
There are many factors that affect their decisions, and they are spoilt for choice. They can buy in any country, they can buy bonds, they can buy commodities, they can buy currencies, or they can chase the AI jackpot. Relative valuations, currency moves, index weights and redemptions can also drive these decisions.
And to be fair, several factors have worked against India in the recent past. These include the oil and commodity shock, tariff tantrums, relatively high valuations, Rupee depreciation, the lack of a sizeable AI trade, and most recently, a potential food inflation shock.
With all due respect to television experts, predicting when FIIs will return is futile. We have no idea when these wars will end, whether others will begin, what Trump might do next, or when the AI trade will fizzle out.
Nor does it make sense to assume they will buy the same stocks they held earlier. Popularity in one era does not guarantee popularity in another. Trying to second guess what another investor may or may not do is a waste of time. For one, we don’t know when they may buy, nor how attractive different stocks may be at the time.
As investors, we need to identify companies or sectors where we expect superior earnings growth at a reasonable price. This is not to deny the impact that foreign buying can have on our markets, but remember that they too will be attracted by earnings growth and “reasonable” valuations.
The old sector labels may not help much in a world where AI is reshaping business models, supply shocks are pushing up costs and higher interest rates are making debt more expensive. Rather than assuming that an entire sector will benefit, it may be more useful to look at individual businesses.
Can they pass on cost increases? Do they have manageable debt? Can they keep growing earnings without constantly needing fresh capital? Can they leverage AI better than others? Can they take advantage of India’s new trade deals?
The important thing is none of this has anything to do with FIIs, or when they return. Trying to predict foreign flows is arguably much more difficult than identifying businesses that can withstand the headwinds, and keep growing earnings.
In other words, make your investment decisions as if the FIIs will not return. Successful investing is not about foreign flows, but a discipline. Build a portfolio that makes sense – competitive advantage, earnings growth, positive cash-flows, low valuation, margin of safety – and all the other boring stuff.
And if you’re right, there’s a good chance that the FIIs (whenever they return) will end up buying some of the same stocks. If so, it will be a bonus. But your investment thesis must stand even if FIIs never come back.

Leave a Reply