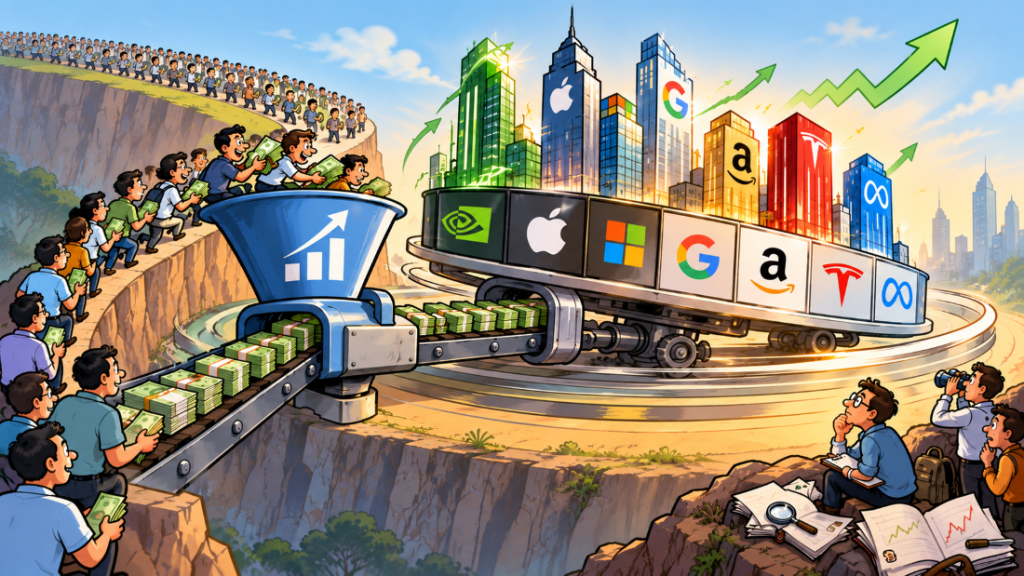
Index funds were designed to follow the market, not to beat it. But what happens when more and more money chases the same index? Could the followers end up influencing the very market they are supposed to track?
The idea behind passive investing is simple. Research going back decades found that most fund managers struggled to beat market indices consistently. Burton Malkiel (author of “A Random Walk Down Wall Street”) and others helped push the idea that investors would be better off buying the “market” than trying to outsmart it.
In 1976, John Bogle made this concept available to ordinary investors through Vanguard’s first index fund. Wall Street initially mocked him for promising merely “average” returns. But low fees proved a formidable advantage, and when ETFs improved access in the 1990s, passive funds took off.
Morningstar’s December 2025 report put passive funds at 55% of assets in US long-term open-ended mutual funds and ETFs. Another study (Chinko & Sammon, The Passive Ownership is Double What You Think It Is) estimated that passive investors (including “closet indexers”) held about a third of the US stock market in 2021. It’s probably higher today.
The irony is that a strategy originally designed to follow the markets, might actually be distorting them.
Consider the feedback loop. A stock rises, attracting momentum investors. If it’s part of an index, its weight increases. Fresh money flowing into index funds is allocated according to new weights. This could impact prices, and in turn reinforce momentum – a self-fulfilling loop.
Then there is a second order effect. Fund managers are judged against index benchmarks. If they underperform for some length of time, they could lose clients – and even their jobs. This encourages “closet indexing” or “index hugging”, so portfolios are closely aligned with the index, with only a small portion available to provide alpha. This further concentrates capital in the same stocks.
Several empirical studies from institutions like the NBER and the Bank for International Settlements (BIS) support the possibility that massive inflows could structurally distort markets. BIS data also suggests an erosion of individual price discovery and heightened systematic risk. However, to be fair, these don’t establish that market excesses are caused by passive inflows.
The current rise (and rise) of the Magnificent Seven (Nvidia, Tesla, Apple, Microsoft, Alphabet, Meta and Amazon) may have started with fundamentals (earnings and growth expectations). But as they’ve grown, they’ve also come to dominate indices. Together, they now account for roughly 35% of the S&P 500. And this index supposedly represents a diversification across 500 companies!
India is not yet at the same stage, but getting there. Domestic index funds are growing, while EPFO and NPS investments via index-linked ETFs add another source of index demand. Foreign portfolio investors bring further complications. Most of them track, or are benchmarked against indices especially those managed by MSCI (Morgan Stanley Capital International).
When foreign investors sell, large Indian stocks see outflows. Falling prices induce pressure from both domestic and overseas index-linked portfolios. This may have contributed to underperformance of large-cap indices relative to the broader market recently.
However, this is hard to prove, as stock prices are influenced by many factors – including fundamentals, geopolitics, inflation, AI hype and of course, the tweets of Mr. President!
Index changes provide a more visible example.
When a stock is added to an index, speculators buy, anticipating index fund purchases. The announcement effectively triggers front-running. The closing auction often sees sharp price movements, as speculators offload and passive funds buy.
In May 2026, MSCI added Federal Bank, MCX, NALCO and Indian Bank to its Global Standard Index. Some reports estimated passive inflows exceeding $1 billion, and similar outflows for deletions. That’s a lot of buying and selling that had nothing to do with fresh data on the companies’ prospects. Similar behaviour is seen when the Nifty or Sensex add or remove stocks.
Of course, proving lasting price distortion is difficult, given the large number of variables that can affect share prices. But, it does raise uncomfortable questions.
Perhaps the real irony is: passive investing works because it doesn’t try to beat the market. But if everyone becomes passive, who will do the price discovery that passive funds depend on? Or do we leave that to the index managers?

Leave a Reply