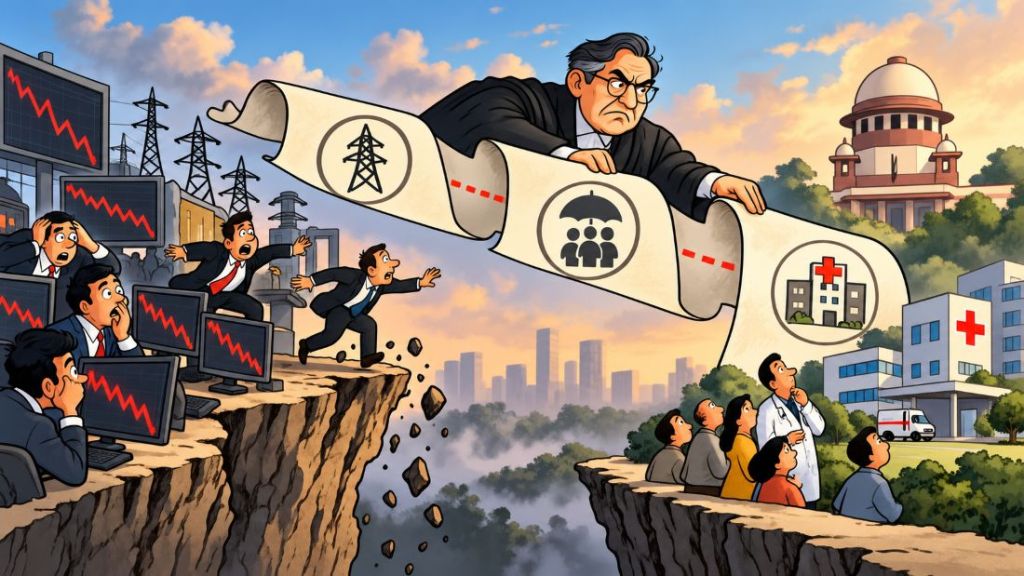
Regulatory risk is again in the spotlight, after IRDAI’s recent proposals to cap insurance expenses and commissions. IRDAI’s discussion paper was released on the 23rd of September and the next day, stocks of insurers, distributors and banks crashed.
The collapse of market favourite, PB Fintech (Policybazaar) was the most dramatic. The stock fell 36% in one day and continued to fall, with the 43% loss (as of 29th Sept) eroding more than ₹37,000 crores of market cap in a week.
A similar episode played in July 2025 when electricity regulator CERC announced market coupling. The shares of IEX lost 28% in a single day, and have fallen almost 48% in 14 months.
It is easy for investors to blame capricious regulators, but these risks were clearly visible.
CERC’s Power Market Regulations 2021, already contained provisions for market coupling. In 2023, a “staff paper” on the subject was released. In 2024, CERC asked Grid India to conduct a “shadow pilot”. So while the exact terms were unclear, the possibility of market coupling was no secret.
Similarly, IRDAI had expressed concerns about commissions and rewards to distributors, back in 2019. Drafts, guidance and frameworks followed in 2022, 2023 and 2024. In 2026, several newspaper reports and statements from the IRDAI Chairman suggested regulation was imminent. Yet, the September guidelines came as a “big surprise”.
This got me pondering about why investors ignore regulatory risk. Maybe we think it won’t happen. Perhaps it’s difficult to include in valuation models. Or we think regulators will be gentle, or the regulation will be delayed by bureaucracy or legal action or some other act of god. Or maybe we simply can’t fight consensus, especially when the stocks are doing well.
Richly valued companies with seemingly impregnable moats tend to be most impacted. IEX was valued at 44 times trailing earnings and PB Fintech >100x, prior to the collapse. When multi-year projections of 25%+ growth with robust margins are invalidated, it’s a double-whammy – reduced earnings growth and shrinking valuations. Interestingly, both stocks had high institutional holdings (IEX – 52%, PB Fintech – 78%) before the bad news hit.
Enough of hindsight, let’s talk about hospitals.
Hospitals are a great business. India faces a huge shortage of quality healthcare, insurance is spreading, the middle class is growing, people are living longer, scale provides considerable operating leverage, and illness does not face recessions.
In addition, they have immense pricing power thanks to information asymmetry. When a family member is ill, worried relatives don’t question their doctor’s choice of hospital. Once inside, we have no idea what a treatment, syringes or drips, or tests and consultation fees cost. Even if we did, we’re in no position to bargain, especially in cases of critical illness.
Little wonder that PE funds are clambering over each other to invest, with inflows crossing $7 billion in the last decade.
It’s ironic that the very success of private hospitals is inviting increasing regulatory scrutiny. But again, this is not new.
The Clinical Establishments Act was passed in 2010, and its rules released in 2012. So far, 19 states have adopted the Central framework or some version of it. The Act requires hospitals to display rates and prescribes that charges be within prescribed ranges. However, more than a decade later, rate ranges have still not been operationalised.
The issue has surfaced repeatedly — in parliament, CCI complaints, numerous studies, court proceedings and government investigations. In August 2026, a Rajya Sabha committee recommended price caps on drugs, devices, room-rents and standardised treatment packages. And on September 29 (as I was editing this), the Supreme Court asked the government why drug prices at hospitals should not be capped. This follows an earlier 2024 directive to find a way to regulate hospital fees.
This is a difficult sector to regulate. Drug and device mark-ups can potentially be capped; but standardising hospital services is far harder given differences in labour, real estate, equipment and case mix. States also differ in their approach.
This has delayed effective regulation for years, and possibly led investors to believe it will never happen. Hospital stocks remain richly valued, with the sector trading at a median P/E of around 50, even after the 29th Sept sell-off.
The direction is clear even if the final nature of regulation is unknown. Hospitals may well take this in their stride given the strong underlying demand trends. However, investors need to ask: How much of today’s valuation depends on pricing power that regulation may eventually challenge?
I am not a registered research analyst or advisor. The above article should not be construed as investment advice or recommendation, but is merely for the purpose of debate and discussion. You should assume that I’m biased and may have a position in any of the stocks mentioned in the article.

Leave a comment